Metro Atlanta home loans · Loan officer and realtor
Know your real numbers before you fall in love with the house.
I read your deal the way an underwriter will, so your offer holds up and your monthly payment has no surprises.
What brings you here?
Free 30 minute call · No credit pull · No obligation · Or call (770) 214‑4072
- Two decades in lending and real estate
- Self employed and investor programs
- Purchase, refinance, and buy and sell together
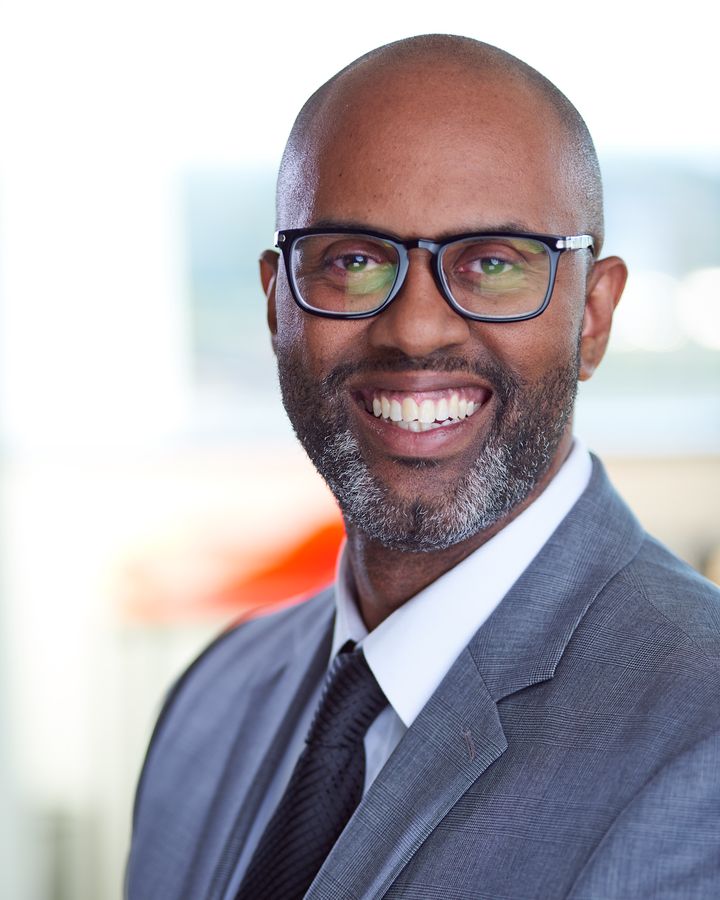
About Mark
I learned the money before I learned the house.
I'm an Atlanta original, born and raised in Brookhaven. Competition built me early.
Football earned me a college scholarship and All Conference honors, and I finished with a degree in Business Management. The game taught me two things I still live by: preparation wins, and nobody wins alone.
That's how I run every loan. I started in mortgage in 2004 at one of the largest lenders in the country, and I learned fast that the rate is the easy part. The real work is building the right loan for your life and getting it to the closing table on time. That's true whether you're a first time buyer competing in a bidding war, moving up and timing two closings, running a business with income that doesn't fit a W2, or a veteran using the benefit you earned. That's where I earn my keep.
Today I lead Mark of Approval Home Loans with NEXA Lending, and every file gets the same game plan: prepare early, keep the whole team in sync, and leave no surprises for the closing table.
- 2004Starts in mortgage
- 2006Adds real estate
- TodayMark of Approval Home Loans
Since 2006 I've also helped hundreds of Atlanta families buy and sell homes, including plenty of complicated deals that needed a creative fix to close. I study this market every day. So when I look at your loan, I read it the way an underwriter will: where the appraisal is likely to land, whether your debt ratios hold, how a seller credit changes your payment, and what could stall a closing three days out. Most people find those problems when it's almost too late. I look for them weeks earlier.
For you, that means a loan plan before you start touring, an offer backed by financing that holds, and a real monthly number before you fall in love with the kitchen.
More about MarkShow less
I hold myself to the same standard I promise you. I'm part of mastermind groups with some of the sharpest people in the business, and they hold me accountable to keep getting better. I take my health just as seriously. I train consistently, eat a plant based diet, and the old football player in me has fallen hard for pickleball. I'm still working on my dink shot.
You'll get the real numbers, the real risks and a straight recommendation. Then you decide.
5559 S Sossaman Rd, Bldg 1, Ste 101
Mesa, AZ 85212
Start here
Which one sounds like you?
Pick your situation. It's a one minute form, and I'll get back to you within one business day with a straight answer.
Buying my first home
“How much house can I actually afford?” Let's find out before you start touring.
Start here (opens in a new tab)Buying my next home
Moving up, downsizing, or relocating? Put the equity you've built to work.
Start here (opens in a new tab)Buying and selling at once
“I have to sell mine to buy the next one.” Here's how to time it.
See your optionsSelf employed
“My tax returns don't show what I really make.” Qualify on bank deposits instead.
Start here (opens in a new tab)Veteran or active duty
Use the VA benefit you earned, often with no down payment and no monthly mortgage insurance.
Start here (opens in a new tab)Buying a rental
Qualify on the property's rent, not your paycheck, with a DSCR loan.
Start here (opens in a new tab)Already under contract?
“Is this a good deal?” Send me your Loan Estimate for a second look before you lock.
Get the Second LookRate Watch
Already own? I'll tell you when refinancing actually makes sense for your loan, and not before.
Join Rate Watch (opens in a new tab)How it works
The Approval Path
Here's exactly what happens after you reach out. Four steps, no surprises.
Reach out
Book a free call or start the secure online application. Neither one commits you to anything.
Get a clear plan
I review your income, credit, and goals, then walk you through your options and estimated costs line by line.
Get approved
You upload documents. I keep your file moving through underwriting, and you always know where it stands.
Close with confidence
You get your Closing Disclosure at least three business days before closing, so nothing on signing day is new.
Free buyer's guide
The Approval Path, in one place.
21 pages on what lenders look at, the documents you'll need, what's really in your monthly payment, and how to keep your closing on schedule. Written for metro Atlanta buyers.
Send me the free guide (opens in a new tab)First name and email. Takes 20 seconds. No credit pull.
Free Loan Estimate review
The Second Look.
Already have an offer from another lender? Send me your Loan Estimate. I'll go through the rate, the fees and your cash to close line by line, and tell you plainly whether it's a good deal. If it is, I'll say so.
Get my Second Look (opens in a new tab)Free. No credit pull. Reply within one business day.
- Upload your Loan EstimateA photo or the PDF works.
- I review it line by lineRate, points, lender fees, title and escrow.
- You get a straight answerKeep your lender, or see what I can offer.
Payment calculator
What would my monthly payment be?
Change any number and the payment updates. The figures below are a sample scenario, not a rate quote, but they're an honest place to start.
Estimated monthly payment
Loan amount
Estimate only. Not a commitment to lend or a rate lock. Actual rate, APR, mortgage insurance, taxes, and payment depend on your credit, loan program, property, and market conditions at the time you apply. FHA and VA loans calculate mortgage insurance and funding fees differently.
Get my real numbers (opens in a new tab)One minute form · No credit pull · I reply within one business day
Loan programs
There's more than one way to get approved.
If a bank told you no, it may have been the wrong loan, not the wrong borrower. Here's what I offer metro Atlanta buyers, homeowners, and investors. Tap any program for the details.
Most popularConventional loansThe most common mortgage in the country, built on Fannie Mae and Freddie Mac guidelines.
- As little as 3% down for some first time buyers
- Mortgage insurance can be removed once you reach enough equity
- Primary homes, second homes, and rentals
Government backedFHA loansInsured by the Federal Housing Administration, built for buyers with smaller down payments or credit that's still growing.
- Down payment as low as 3.5% for qualified borrowers
- More flexible credit guidelines
- Gift funds allowed for the down payment
Government backedVA loansA benefit earned through service, for eligible veterans, active duty members, and some surviving spouses.
- No down payment required in many cases
- No monthly mortgage insurance
- Certificate of Eligibility required
Self employedBank statement loansQualify using your business or personal bank deposits instead of tax returns that show heavy write offs.
- Typically 12 or 24 months of statements
- Made for business owners and 1099 earners
- Primary homes, second homes, and rentals
Alternative documentationNo ratio loansNo debt to income calculation. The loan leans on your credit, assets, and down payment instead.
- Useful when income is hard to document
- Larger down payment usually required
- Reserves and credit carry more weight
InvestorsDSCR loansQualify an investment property on its rental income compared to its payment, not your personal income.
- Debt service coverage ratio drives approval
- No personal income verification
- Room to grow past conventional limits on financed properties
- Close in an LLC in many cases
Build newConstruction loansFinance the lot and the build, with funds released in draws as the work gets done.
- Construction to permanent options
- Draw schedule tied to build milestones
- Plans, budget, and builder reviewed up front
Buying and selling at the same time
Sell one home. Buy the next. Skip the juggling act.
It's the most stressful move in real estate: two contracts, two closings, and a down payment tied up in the house you're still living in.
As both a metro Atlanta realtor and a loan officer, I plan both sides together, so your sale, your loan, and your closing dates actually line up.
Book a free call (opens in a new tab)HELOC and bridge financing availability depends on your equity, credit, and property. If I represent you as both agent and lender, you'll get any required disclosures up front.
Sell first, then buy
Close on your current home, then use the proceeds for your next down payment.
- Best when
- You want a firm budget and one mortgage at a time.
- Watch for
- You may need a short term rental or a rent back agreement after closing.
Buy first, then sell
Tap your current equity with a HELOC or bridge financing, move in, then sell.
- Best when
- You've found the right home and don't want a sale contingency weakening your offer.
- Watch for
- Qualifying with both payments for a while. Open a HELOC before you list, since most lenders won't open one on a home that's already for sale.
Close both the same week
Line up both closings back to back, with proceeds from your sale flowing into your purchase.
- Best when
- Both deals are solid and the timing is predictable.
- Watch for
- A delay on one side ripples into the other. Tight coordination between agents, lender, and title is everything.
Refinance and home equity
Should I refinance? Let the numbers decide.
A lower rate isn't automatically a better deal. The closing costs have to pay for themselves before you move or refinance again. Tap any option for the details, then check the math with the calculator.
Any loan typeRate and termReplace your current loan with a lower rate, a shorter term, or both.
Also a common way to move from FHA to conventional and drop monthly mortgage insurance.
Conventional, FHA, VACash out refinanceTake a new, larger loan and walk away with the difference in cash for renovations, debt payoff, or investing.
Conventional cash out is typically capped at 80% of your home's value.
Existing VA loansVA streamline (IRRRL)A faster refinance built to lower the rate on your current VA loan, often with no appraisal and lighter paperwork.
Available when you already have a VA loan. The new loan must lower your rate or move you from an adjustable rate to a fixed rate.
Existing FHA loansFHA streamlineLower the rate on your current FHA loan with reduced documentation and often no appraisal, as long as the new loan gives you a real benefit.
Your current FHA loan needs a solid recent payment history, and the new loan must give you a clear benefit, such as a lower payment.
Home equity lineHELOCBorrow against your equity without touching your first mortgage rate.
Draw what you need, when you need it. Rates are usually variable.
Break even calculator
How long until a refinance pays for itself?
Sample numbers, not a quote. This compares principal and interest only. It doesn't account for restarting your loan term, total interest paid, or escrow changes, which we'd review together.
Check my refinance options (opens in a new tab)Questions
Questions I hear all the time
Can I get a mortgage if I'm self employed?
Yes. Traditional loans use your tax returns, which can understate income after business write offs. A bank statement loan looks at 12 or 24 months of deposits instead. Rates and down payment requirements are usually higher than conventional loans, so it's worth comparing both.
What is a DSCR loan?
DSCR stands for debt service coverage ratio. The lender compares the property's expected rent to its monthly payment (principal, interest, taxes, insurance, and HOA). If the rent covers the payment, the loan can qualify without using your personal income. It's for investment properties only.
How much do I need for a down payment?
It depends on the loan. FHA can be as low as 3.5% for qualified borrowers, VA often requires nothing down for eligible veterans, and investment and alternative documentation loans usually need more. You'll also need money for closing costs and, on some loans, reserves.
What does "no ratio" mean?
A no ratio loan skips the debt to income calculation. Approval leans on your credit, assets, and down payment. It can help when income is real but hard to document, and it usually comes with a larger down payment and a higher rate.
When does refinancing make sense?
When the savings pay back your closing costs before you plan to move or refinance again. Divide your closing costs by your monthly savings to get your break even point in months. Refinancing can also make sense to remove mortgage insurance, switch from an adjustable to a fixed rate, shorten your term, or pull cash out, even when the payment doesn't drop.
Can I buy my next home before I sell my current one?
Often, yes. It depends on whether you qualify carrying both payments for a while, how much equity you have, and whether a HELOC or bridge option fits. If a HELOC is part of the plan, open it before you list, since most lenders won't open one on a home that's already for sale.
Does applying hurt my credit?
Booking a call doesn't touch your credit. A full application usually includes a credit pull, and mortgage inquiries within a short shopping window are typically treated as a single inquiry by credit scoring models.
Already under contract with another lender. Can I still switch?
Often yes, as long as there's time before closing. Send over your Loan Estimate and I'll compare the rate, fees, and cash to close line by line so you can decide with real numbers.
Get your Mark of Approval.
Bring your questions. I'll bring the numbers. Free 30 minute call, no credit pull, no obligation. Serving metro Atlanta and all of Georgia.
- One advisor, start to finish
- No call center
- Your info never gets sold to a lead list
Not ready yet? Join Rate Watch (opens in a new tab) and I'll reach out when the numbers make sense.